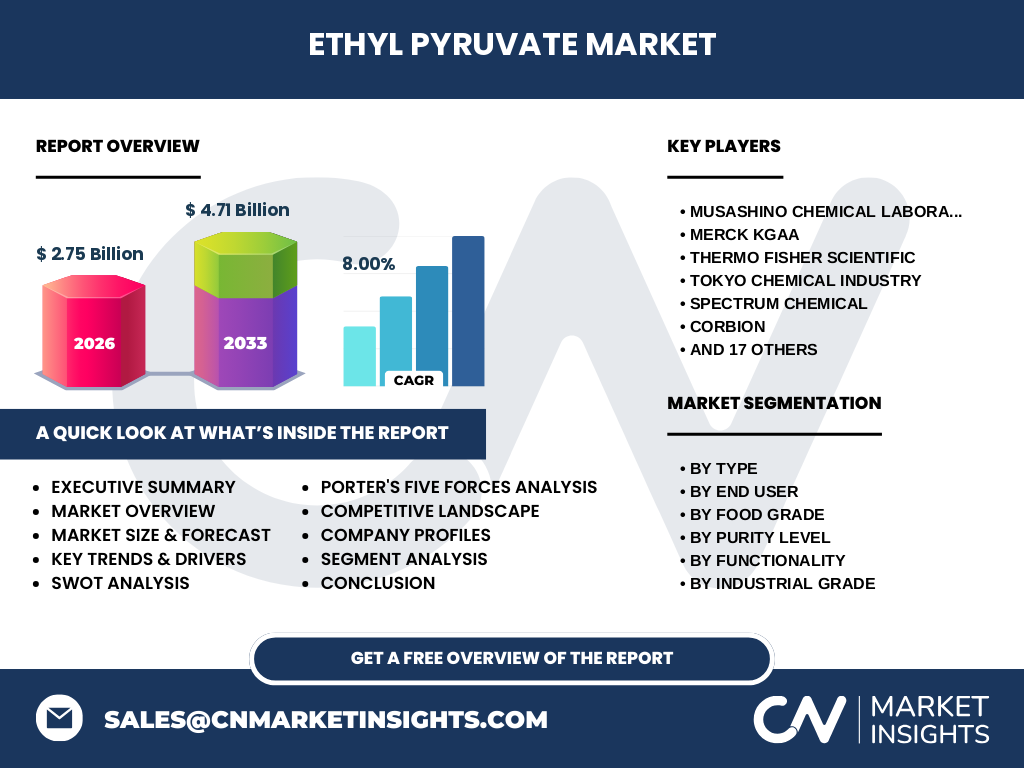
Market overview of the Ethyl Pyruvate Market
Our analysis indicates that the Ethyl Pyruvate Market is valued at 2.75 Billion in 2026. This vital chemical intermediate serves high-value applications across pharmaceutical synthesis, specialized food processing, and advanced cosmetic formulations, driven by stringent purity demands.
Structural Growth Drivers and Restraints
Growth is propelled by rising demand for anti-inflammatory agents and advanced antioxidants. However, supply chain bottlenecks for raw pyruvic acid precursors and strict regulatory compliance enforced by bodies like the FDA and EMA create notable restraints for chemical manufacturers.
Emerging trends and growth patterns in Ethyl Pyruvate Market
The shift toward green chemistry has accelerated adoption. Companies are optimizing synthetic routes to improve yield for Ninety Nine Percent Purity grades, reducing waste and aligning with global sustainability directives in specialty chemical production.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and logistical bottlenecks across major ports. Recovery has been robust, driven by surging pharmaceutical R&D expenditures and heightened demand for pharmaceutical grade chemical intermediates used in life sciences.
Competitive benchmarking and strategic dynamics
The landscape features established innovators like Merck KGaA, Thermo Fisher Scientific, and Musashino Chemical Laboratory. Market concentration is moderate to high, with leaders leveraging extensive distribution networks and proprietary synthesis technologies to maintain pricing power.
Executive summary of key findings
Our research projects the Ethyl Pyruvate Market industry trends to expand from 2.75 Billion in 2026 to 4.71 Billion by 2033, representing a robust 8.00% CAGR. High-purity pharmaceutical segments remain the primary value pool.
Market forecast from 2027 to 2033
Driven by expanding biotechnology applications and increased utilization as a chemical intermediate, the market is set for sustained acceleration, achieving a projected valuation of 4.71 Billion by the end of 2033.
Segmentation analysis across types and end users
The market divides by type into Pharmaceutical Grade, Food Grade, and Industrial Grade. End-user categories span Pharmaceutical And Biotechnology Companies, Food Processing Industry, Cosmetic Manufacturers, and Research Institutes, each demanding specific purity profiles.
Geographic distribution and regional performance
North America and Europe dominate consumption due to advanced pharmaceutical infrastructure. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by expanding chemical manufacturing capacities in India, China, and Japan.
In-depth regional review of key markets
Localized manufacturing constraints in Western Europe are offset by strong R&D investments. In contrast, Asia-Pacific benefits from cost-competitive raw material access, supporting regional players like Evans Chem India Pvt. Ltd. and Aarambha Agro Processing Unit.
Company profiles and strategic positioning
Key participants such as Corbion, BASF SE, and Tokyo Chemical Industry focus on high-purity product differentiation. Strategic partnerships and regional expansions allow firms like Spectrum Chemical and Ashland Inc. to secure robust market share.
Porter's Five Forces analysis
Supplier power remains moderate due to specialized precursor requirements. Rivalry is intense among established chemical giants, while threat of substitutes is low given the unique anti-inflammatory and antioxidant functionality of ethyl pyruvate.
SWOT analysis of the sector
Strengths include versatile chemical intermediates and potent antioxidant properties. Weaknesses involve high production costs. Opportunities lie in emerging cosmetic applications, while strict regulatory hurdles pose ongoing threats to smaller market entrants.
Value chain analysis and industry structure
Value flows from upstream petrochemical or bio-based raw material suppliers through complex synthesis processes managed by leaders like Jungbunzlauer and Muby Chemicals, ultimately reaching downstream pharmaceutical and food processing end-users.
Investment insights and strategic recommendations
Stakeholders should prioritize investments in high-purity pharmaceutical grade production facilities. Capitalizing on green synthesis methods offers a strong competitive advantage amidst tightening global environmental regulations.
Conclusion and key takeaways
With a projected 8.00% CAGR reaching 4.71 Billion by 2033, the market offers lucrative avenues for innovation, particularly in high-purity pharmaceutical and specialized antioxidant applications.
Research methodology and data triangulation
Our baseline estimates combine exhaustive primary stakeholder interviews with chemical manufacturers, trade registry import-export data, and macroeconomic secondary indicators to ensure robust, validated market sizing.
Scope of the report and coverage parameters
This report covers global market sizing, regional performance, granular segmentation by purity and functionality, and competitive landscape assessments for the timeframe spanning 2026 through 2033.
Recent developments in the industry
Recent strategic moves include capacity expansions by specialty chemical firms and collaborative research agreements between LGC Group and academic research institutes aimed at novel pharmaceutical applications for ethyl pyruvate.